

 324 / 414

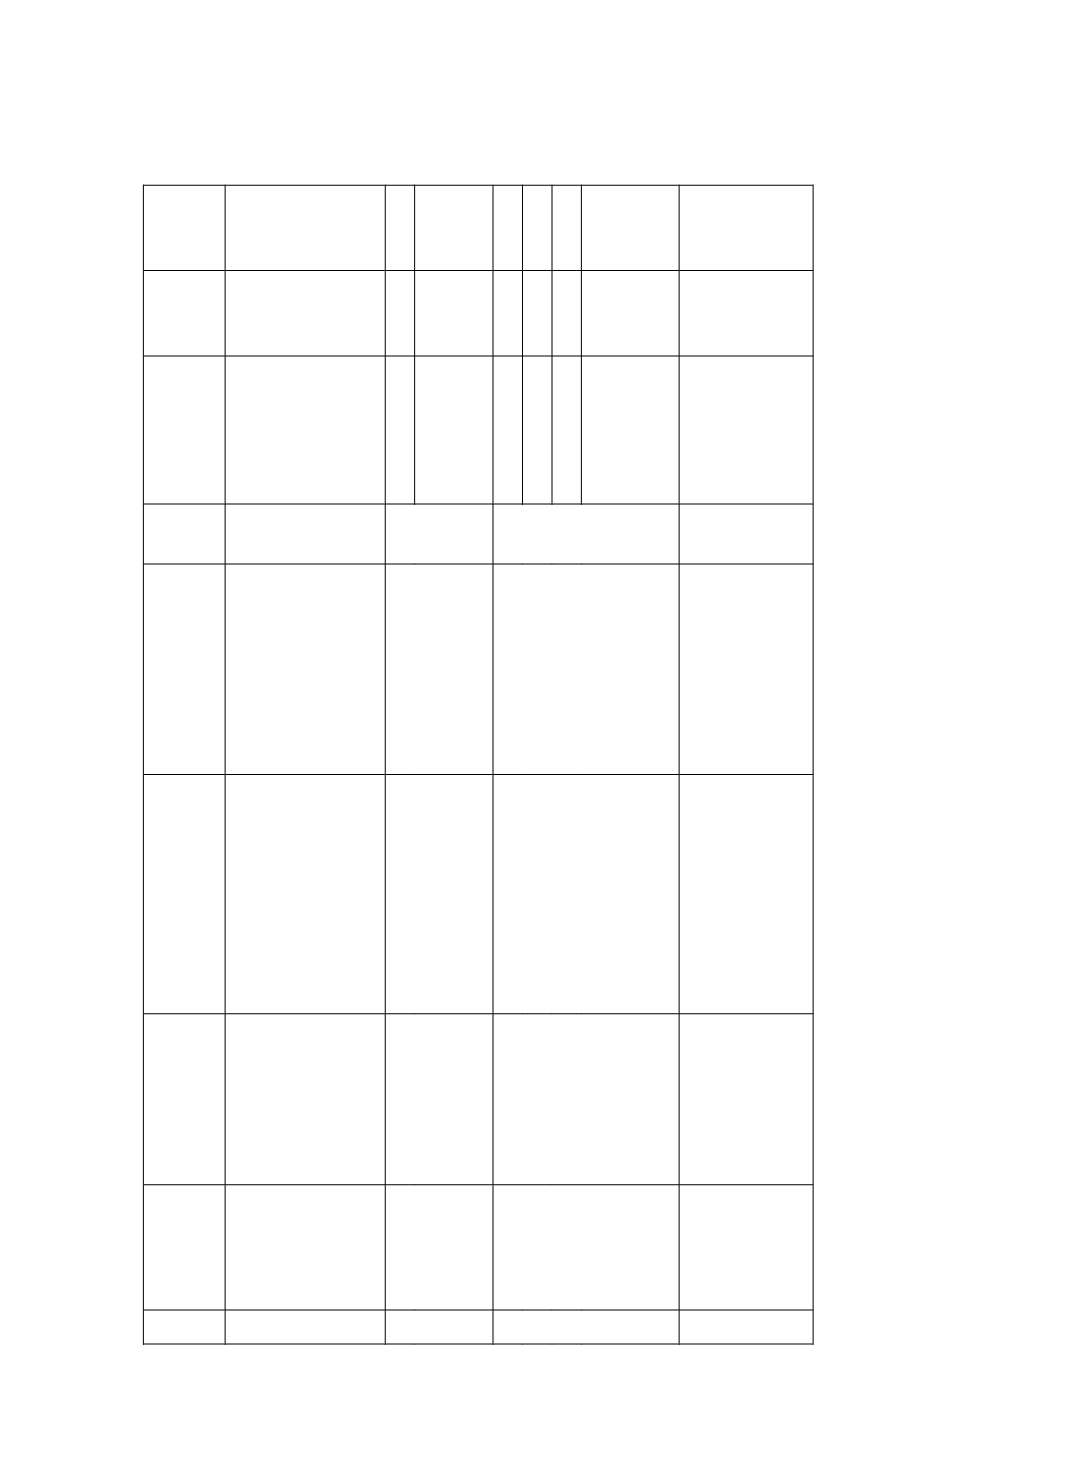
亞洲地區審計品質研究回顧
324
國
家
證券主管機關 審計主管機關 會計準則制訂機關 審計準則制訂機關
是否
加入
IFIAR
交易所
上市公司
家數
(12
/ 2014)
市值十億
美金
(12
/ 2014)
南
韓
Financial
Supervisory
Service
Financial
Supervisory
Service
(隸屬
Financial
Services
Commission
)
Korean Accounting Institute
(KAI)
(歸屬於獨立機構)
2011
年強制適用
IFRS
Korean Institute of
Certified Public
Accountants
(歸屬會計專業團體
)
是
南韓證券期貨交
易所
1,864 1,212.8
中
國
China
Securities
Regulatory
Commission
Ministry of Finance
(MOF)
Ministry of Finance
(歸屬於政府)
2007
年起會計準則與
IFRS
趨同
The Chinese Institute of
Certified Public
Accountant (CICAP)
(歸屬於會計專業團體)
否
上海證券交易所
995 3,932.5
深圳證券交易所
1,618 2,072.4
日
本
Financial
Services
Agency
Certified Public
Accountants &
Auditing Oversight
Board
(隸屬
Financial
Services Agency
)
Financial Accounting
Standards Foundation
(FASF)
(歸屬於獨立機構)
與
IFRSs
趨同,符合條件之
日本上市公司可自願性適用
IFRSs
Financial Services
Agency/ Japan Institute
of Certified Public
Accountant (JICPA)
(政府
/
會計專業團體
)
是
東京證券交易所
3,470 4,378.0
名古屋證券交易所
298 1,288.7
札幌證券取引所
56
440.6
福岡證券取引所
114*
536.1
以
色
列
Israel
Securities
Authority
(ISA)
Israel Securities
Authority (ISA)
Israel Accounting Standards
Board
(歸屬於獨立機構)
上市公司
2008
年後適用
IFRSs
Institute of Certified
Public Accountants in
Israel
(歸屬會計專業團體)
否
特拉維夫證券交
易所
473 200.5
註一:
IFIAR
全稱為
International Forum of Independent Audit Regulators (IFIAR)
。
註二:交易所資料取自
World Federation of Exchanges
。日本札幌證券取引所(亦即臺灣所稱之交易所)、福岡證券取引所與巴基斯坦三個交易
所之資料取自交易所網頁。
註三:國際會計準則採用狀況統計自
Deloitte
網頁
: http://www.iasplus.com/en/jurisdictions
。最後搜尋時間為:
2015
年
4
月
30
日。